Harrisburg & Central PA
Tropical Storms and the Susquehanna: What Riverfront Homeowners Must Know
The remnants of tropical systems reach Central PA regularly. They bring three separate problems, and only two of them are covered by your homeowners policy.
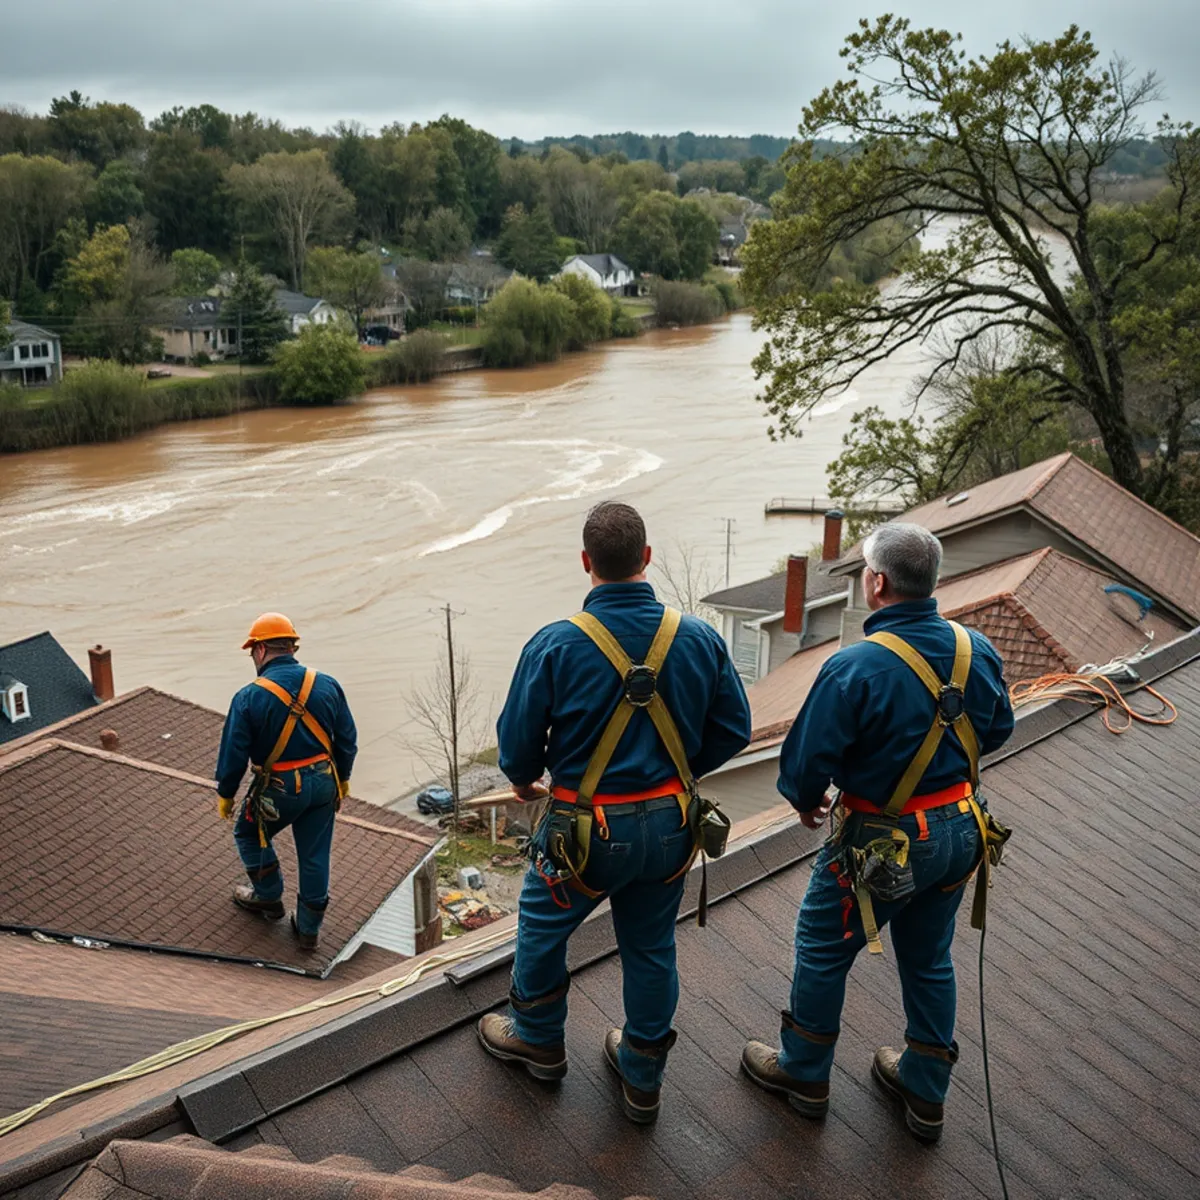
The short answer
Tropical remnants bring three separate problems to this valley: sustained wind, wind-driven rain that gets under courses vertical rain never touches, and flooding. The first two are covered by homeowners insurance. Flood never is — that requires a separate policy with a waiting period.
Central Pennsylvania is far enough inland that people forget it is on the receiving end of tropical systems. The Susquehanna basin's flood history says otherwise — Agnes in 1972 remains a benchmark event, and Lee in 2011 put the river back into major flood stage within most homeowners' memory.
By the time a tropical remnant reaches this valley it has lost its wind structure but not its water. What arrives is prolonged, heavy rainfall over a large basin that drains into one river, plus enough wind to find every weakness on a roof.
Three separate problems, and it matters enormously which one you have.
Problem 1: wind
Even a decayed tropical system produces sustained wind well beyond a typical thunderstorm, and it arrives from directions our roofs are less accustomed to.
The Susquehanna valley channels systems moving through and intensifies gusts. Riverfront properties in Shipoke, along Front Street, in Wormleysburg and Marysville have nothing between them and the open water.
Wind damage is covered by standard homeowners insurance. That is the important part of this section.
Problem 2: wind-driven rain
This is the underrated one. Sustained rain driven horizontally behaves completely differently from rain falling vertically.
It gets under shingle courses that shed vertical rain perfectly well. It finds its way behind siding at roof-to-wall intersections. It penetrates ridge vents that were never designed for water arriving sideways at forty miles an hour. And it exploits every marginal flashing detail simultaneously.
Homeowners frequently report leaks during a tropical remnant in places that have never leaked before and never leak again. That is wind-driven rain, and it is generally a covered wind loss — though it needs documenting clearly as such.
Problem 3: flooding
And here is the distinction that matters most: flood is never covered by a homeowners policy. Not in Pennsylvania, not anywhere. Rising water requires separate flood insurance through the National Flood Insurance Program or a private carrier.
That is why the wind-versus-flood determination after a tropical event is such a consequential question. Damage from wind and wind-driven rain goes to your homeowners carrier. Damage from rising water goes to a flood policy, if you have one.
If you own near the river in Harrisburg, Steelton, Middletown, Dauphin borough or West Fairview, know which policies you actually hold before a storm is in the forecast. Flood policies typically have a waiting period before coverage takes effect, so buying one when a system is already tracking north does not help.
Before a tropical system arrives
- Clear gutters and downspouts completely — a storm dropping several inches over a day will overwhelm a partially blocked system immediately
- Secure or remove loose items from the yard and any flat roof — anything that can become a projectile
- Check and photograph your roof's current condition — a documented before-state makes any subsequent claim far simpler
- Trim limbs that overhang the roof, if there is time
- Locate your policies and know your deductibles, including any separate wind deductible
- Charge everything and prepare for outages — the practical basics matter
After the storm
Document before you touch anything
Photographs and video of everything: the roof, the exterior, every interior water mark, and — critically — high-water marks if there was flooding, because they establish rising water versus roof intrusion.
Distinguish the water sources
Water from above and water from below are different claims to different policies. Note where each began.
Mitigate and keep receipts
Tarping, extraction, drying. Required under your policy and generally reimbursable.
Get a roof inspection even if nothing leaked
Sustained wind breaks seal strips. A roof that held through the storm may be unbonded and will fail in the next one.
File promptly with the specific event
Named storms make this straightforward. Reference the storm and the date.
What riverfront homeowners should build in
Two things beyond the standard specification.
First, wind-rated detailing as default: high-wind shingles nailed to the six-nail pattern, starter strip at rakes as well as eaves, and ridge cap rated to the same wind speed as the field. On the most exposed elevations, standing seam metal genuinely earns its cost.
Second, drainage that moves water away from a building already sitting on saturated ground. Downspouts extended well clear of the foundation, sized to carry the peak flow, and discharging somewhere that is not the basement wall. It is the cheapest thing on the estimate and on a river-plain lot it is the most valuable.
The longer history is in flooding and your roof: lessons from Agnes, Lee and the 1996 ice jam.
What this means for your roof
Know which policies you actually hold before a system is in the forecast, because a flood policy bought as a storm tracks north will not help you. And after the storm, document the water sources separately — high-water marks establish rising water, ceiling stains establish roof intrusion, and they go to different insurers.
Then get inspected even if nothing leaked. Sustained wind breaks seal strips invisibly, and a roof that held through this storm may be unbonded for the next one. See storm damage restoration.
Questions we get about this
Is wind-driven rain covered by homeowners insurance?
Generally yes, as a wind loss — but it needs documenting as one. Wind-driven rain produces leaks in places that have never leaked and never will again, which can read as a pre-existing defect unless the report ties it to the storm.
How do I prove flood damage versus wind damage?
Photograph the high-water marks and the direction of staining. Rising water leaves a horizontal line and works upward from the floor; roof intrusion works downward from the ceiling. Where both happened, documenting them separately is what keeps two claims from cancelling each other out.
Should riverfront homes have different roofs?
Different detailing rather than different materials. High-wind rated shingles nailed to the six-nail pattern, upgraded starter strip at the rakes and matched ridge cap handle the exposure. On the most exposed elevations standing seam metal genuinely earns its cost.
Need help with this in Harrisburg?
We are a licensed and insured roofing contractor based at 1000 N Cameron St in Harrisburg. Free inspections, written reports and honest recommendations.
Related services
Areas mentioned