Cost & Insurance
How to File a Storm Damage Roof Insurance Claim in PA (Step by Step)
Nine steps from the storm to the final payment, including the one hour that decides more about your settlement than everything else combined.
The short answer
Document before you touch anything, mitigate and keep the receipts, get an independent inspection before you file, report with the specific event date, and attend the adjuster meeting with your contractor present. That last hour decides more about your settlement than every other step combined.
A storm roof claim is not complicated, but it has a sequence, and doing the steps out of order costs money.
This is the process as we run it with Harrisburg homeowners, start to finish. The single highest-leverage moment is step six — the adjuster meeting — and almost everything before it exists to make that hour go well.
Step 1 — Document before you touch anything
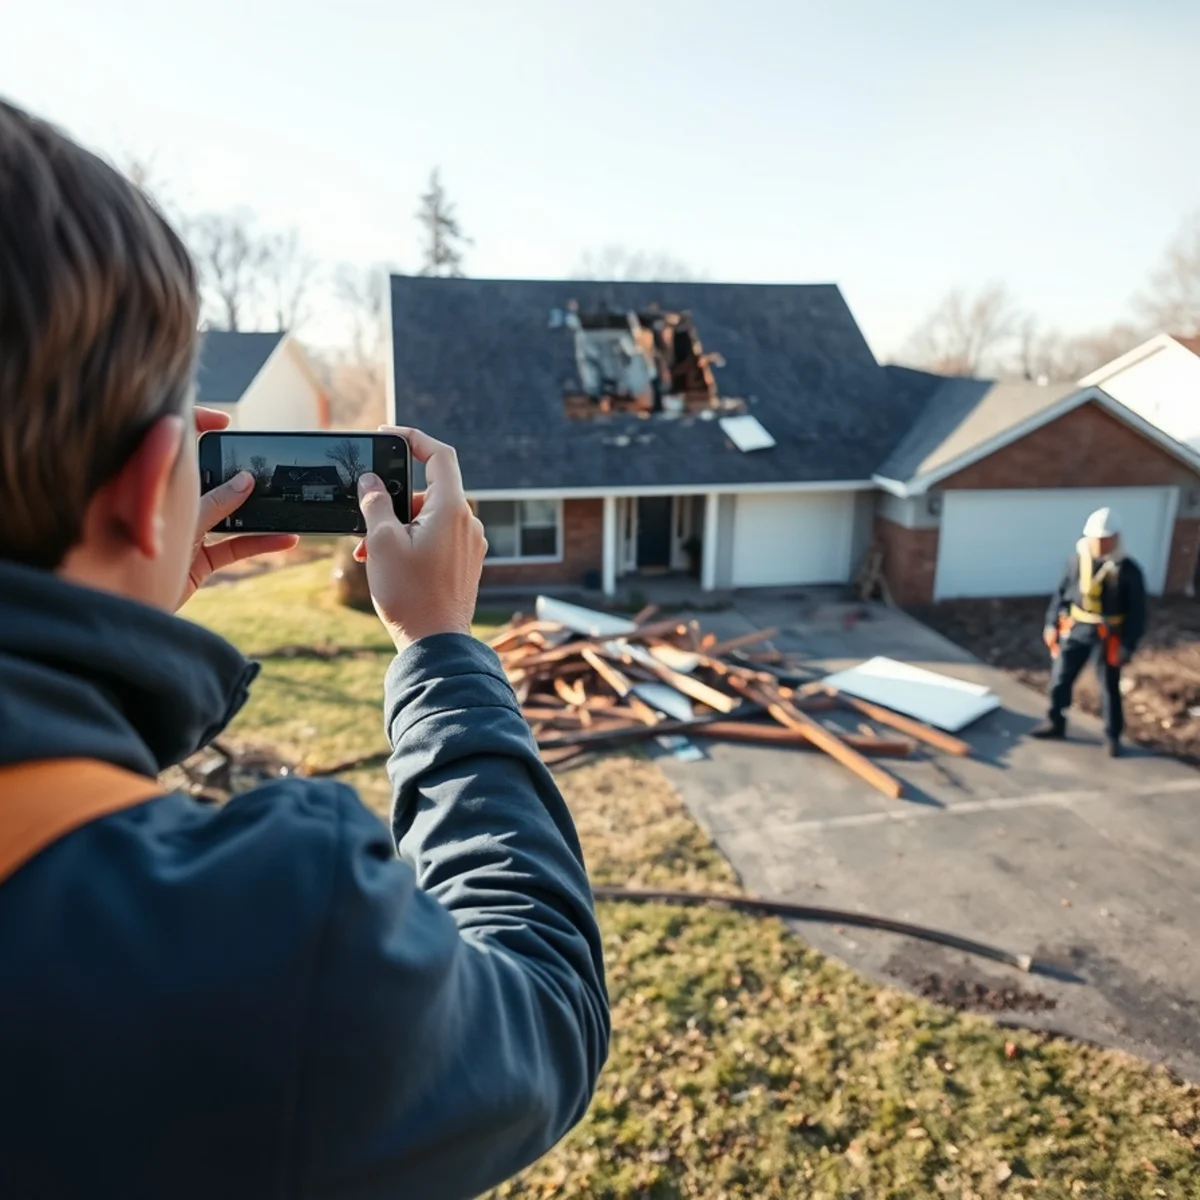
Dated photographs and video of the roof from the ground, every elevation, all interior damage, and any hail, splatter marks or debris. Timestamps come free on every phone and they are evidence.
This happens before cleanup, before tarping, before anyone gets on the roof. Evidence you did not capture does not exist as far as a claim is concerned.
Step 2 — Mitigate, and keep the receipts
Your policy requires you to take reasonable steps to prevent further damage. Emergency tarping, temporary repair, water extraction and drying all qualify, and the cost is generally reimbursable as part of the claim.
Keep every itemized invoice. We deliberately write emergency invoices so the line items map onto claim software categories rather than arriving as an unexplained lump sum.
Step 3 — Get an independent inspection first
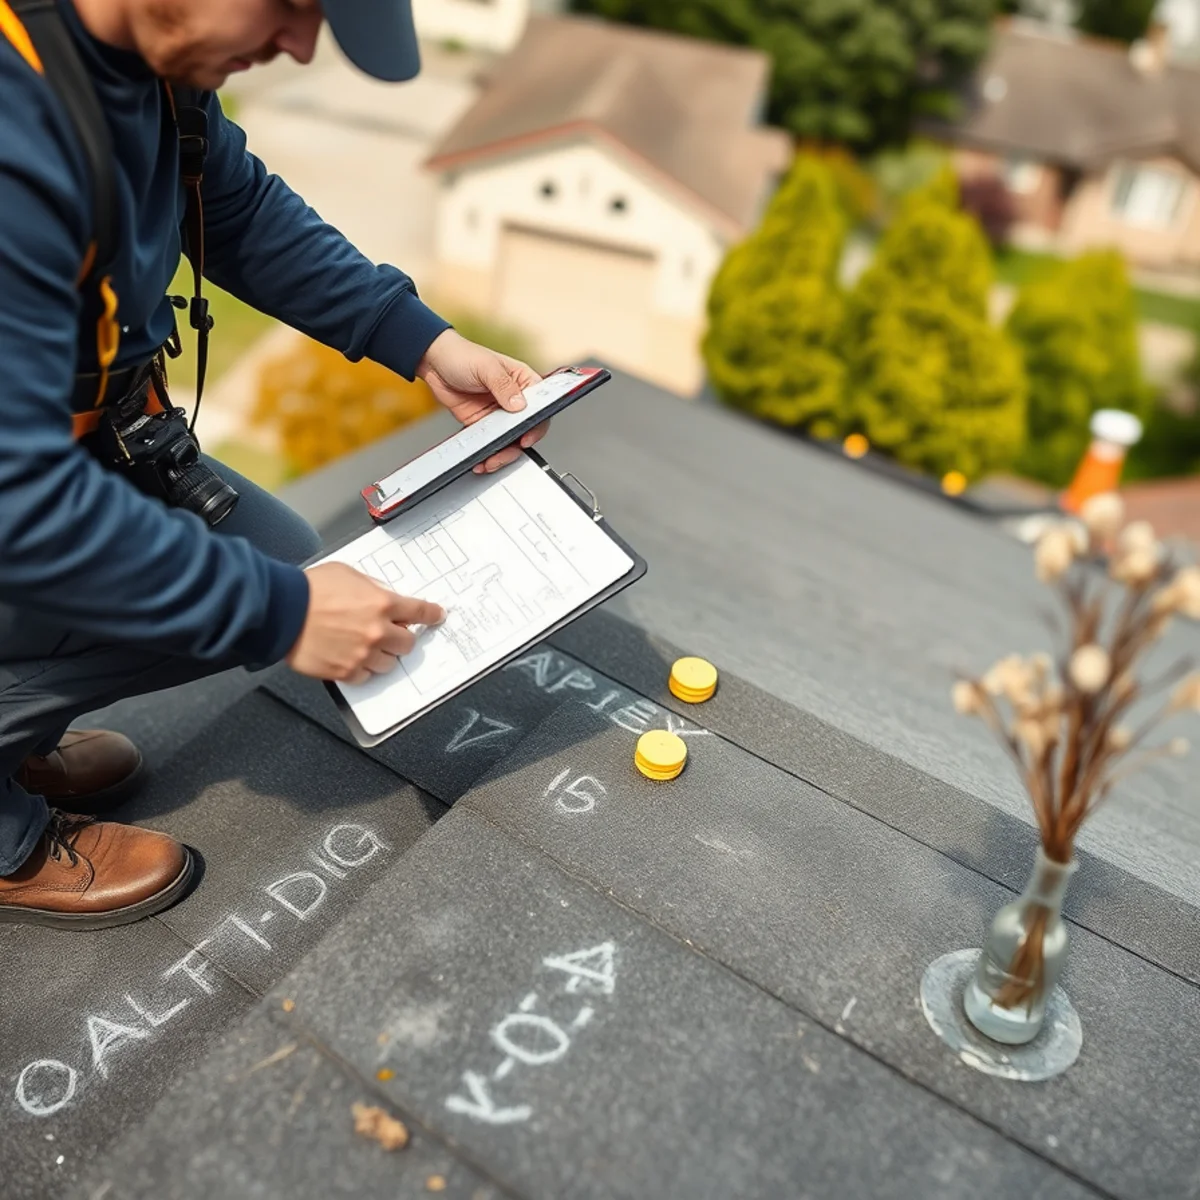
Before you call the insurer, know what you have. A professional inspection produces a roof diagram, per-slope damage counts, test squares where hail is involved, soft-metal photographs and an attic check.
That does two things. It tells you whether you actually have a claim worth filing, which sometimes saves you from putting a pointless claim on your record. And it means that when the adjuster arrives, there is already an evidence-based scope on the table.
Step 4 — File with the right event date and description
Call your insurer or file online. Reference the specific storm and its date. Describe what happened rather than what you conclude: 'wind on the evening of the 14th removed shingles from the west slope and water entered the upstairs bedroom' is a claim. 'My roof has been leaking' is an invitation to categorize it as wear.
Write down your claim number, the adjuster's name and contact, and the date of every call. Claims involve a lot of people and a written log saves you repeatedly.
Step 5 — Prepare for the inspection
Have ready: your photographs and video, the mitigation receipts, your contractor's report and diagram, and access to the attic. Clear the path to any interior damage.
Confirm the appointment time with your contractor so they are on site. This is the step people skip, and it is the one that matters most.
Step 6 — Attend the adjuster meeting with your contractor
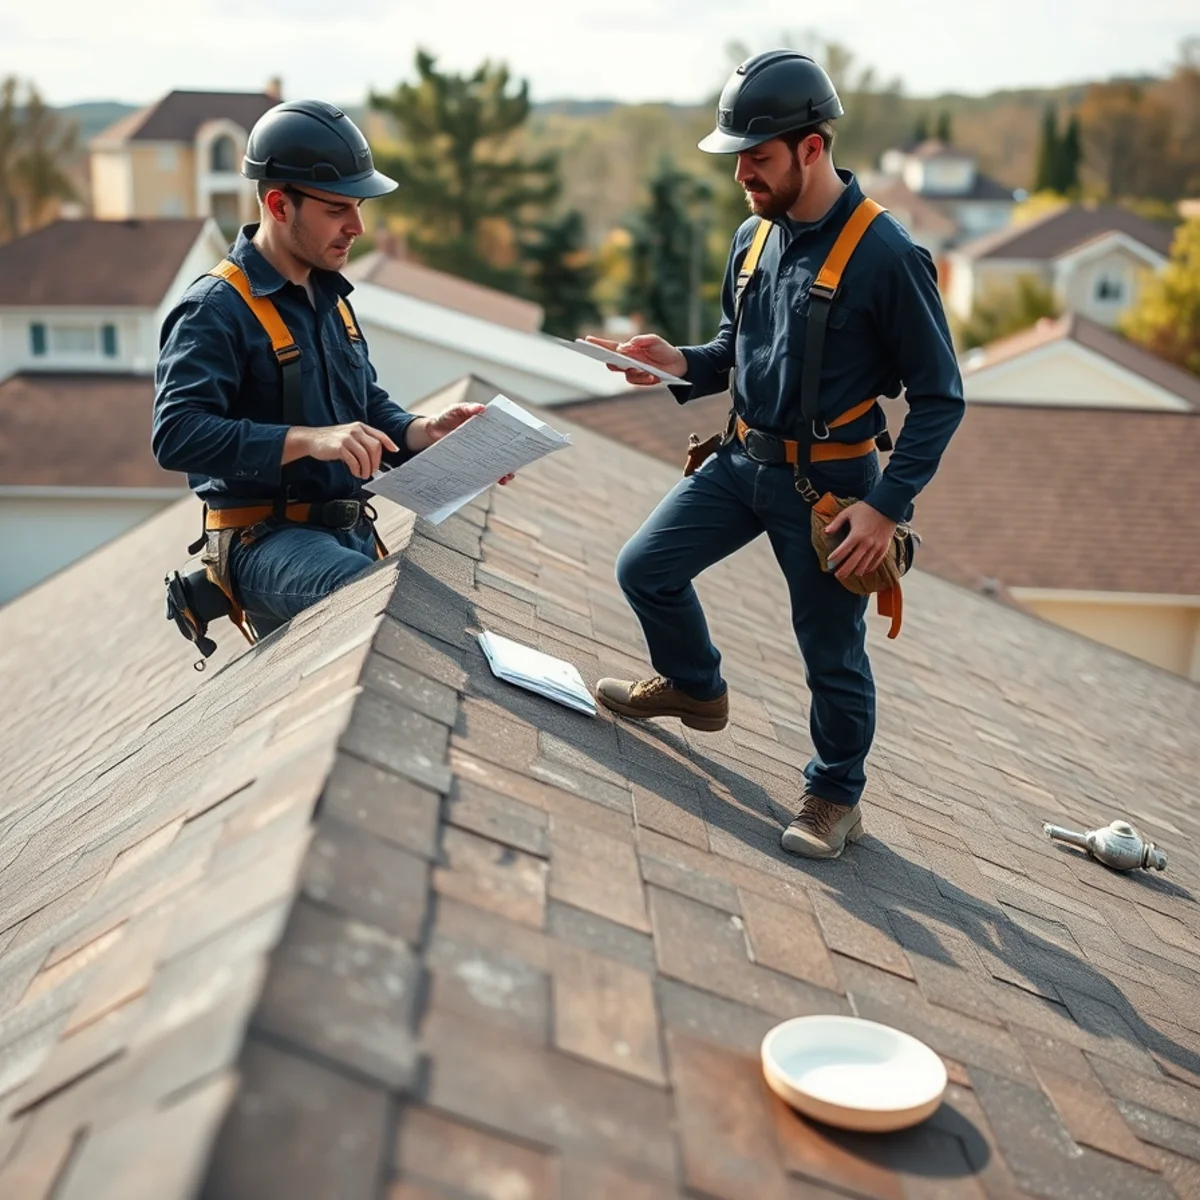
This hour is worth more than everything else in this article combined.
An adjuster after a significant Dauphin County storm may be working through dozens of properties that week. They are not adversaries and most are conscientious, but they are moving fast, and it is entirely normal for damage on a back elevation or a dormer face to go unrecorded simply because nobody walked that slope.
Your contractor being there — with a roof diagram, marked test squares and a per-slope count — changes that. It is a technical conversation between two people who both know what they are looking at, and it consistently produces a more complete scope than a homeowner standing in the driveway can.
Step 7 — Review the scope line by line
You will receive an estimate generated in claims software. Read it against what the job actually requires.
- Is ice and water shield included, and at the right coverage?
- Is drip edge included at eaves and rakes?
- Is ridge vent included, and intake ventilation where it is needed?
- Are steep charges applied if your pitch warrants them?
- Are high charges applied for a second or third story?
- Is starter strip on there as its own line?
- Are all damaged slopes included, or only the ones the adjuster walked?
- Are gutters, siding, screens and soft metals included where they were damaged?
- Is debris disposal at a realistic tonnage?
Step 8 — Supplement anything missing
A supplement is a documented request to add legitimately required scope that was not in the original estimate. It is a completely routine part of the process, not a confrontation.
Supplements succeed when they are specific and evidenced: photographs, the manufacturer's installation requirement, the code provision, or the measured quantity. They fail when they are a general assertion that the settlement is too low.
Step 9 — Complete the work and release depreciation
On a replacement cost policy, the first payment is the actual cash value — the estimate minus depreciation and your deductible. Once the work is finished and you submit the final invoice and completion documentation, the withheld depreciation is released.
This is why documentation at the end matters as much as at the beginning. We provide a completion package with final photographs specifically so recoverable depreciation gets released without a second round of correspondence.
Two things that are never acceptable
First, any contractor offering to waive, absorb, discount or 'take care of' your deductible. In Pennsylvania that is insurance fraud. It voids your claim, and it exposes you personally.
Second, exaggerated or manufactured damage. Beyond being fraud, it poisons the well for every legitimate claim in the county — adjusters get more skeptical, and honest homeowners pay for it.
If a contractor proposes either, that is the end of the conversation. Our approach is on our storm damage restoration page.
What to do next
The steps are not complicated but the order is load-bearing. Evidence before mitigation, mitigation before the adjuster, and your contractor on the roof when the adjuster is on it. Claims that go badly almost always went out of order somewhere near the start.
Two things are never acceptable, whatever a door-knocker tells you after a storm: a contractor offering to cover your deductible, and exaggerated or manufactured damage. Both are fraud in Pennsylvania and both void your claim. See storm damage restoration.
Questions we get about this
Do I need a public adjuster for a roof claim?
Usually not. A contractor who documents properly and attends the inspection covers most of the same ground at no separate fee. Public adjusters take a percentage of your settlement and are most useful on large, complex or genuinely disputed losses.
What if the insurance scope leaves out work my roof needs?
That is what a supplement is for, and it is routine rather than confrontational. Supplements succeed when they are specific and evidenced — photographs, the manufacturer's installation requirement, the code provision, or the measured quantity.
Can I choose my own contractor for storm repairs in PA?
Yes. Your insurer may suggest a preferred vendor but the choice is yours. What matters is that whoever you pick documents properly, will attend the adjuster inspection, and will still be at the same address when a warranty question comes up in year six.
Need help with this in Harrisburg?
We are a licensed and insured roofing contractor based at 1000 N Cameron St in Harrisburg. Free inspections, written reports and honest recommendations.
Related services
Areas mentioned